Does homeowners insurance cover hail damage to a roof in Texas?
Most Texas homeowners policies cover hail damage to a roof, minus your deductible, when the hail caused functional damage such as bruised or cracked shingles. Wear from age is not covered, and some policies pay only the depreciated value of an older roof or exclude cosmetic damage. Have the roof inspected before you file, so you know the damage is there.
Hail is a covered peril on most Texas policies, and the details are in the declarations page
The standard homeowners forms written in Texas treat hail and wind as covered causes of loss. What varies from one policy to the next is how much the carrier pays and how much you pay first. Your declarations page lists your wind and hail deductible, which in much of North Texas is a percentage of the dwelling coverage rather than a flat dollar amount. A 1% deductible on a home insured for $400,000 is $4,000.
Look for two other things. The first is whether roof claims are settled at replacement cost or actual cash value. Replacement cost pays for a new roof, usually in two checks, with the second released once the work is done. Actual cash value subtracts depreciation for the roof’s age, which can leave an older roof paying out far less than a replacement costs. The second is any cosmetic damage exclusion, which lets the carrier decline dents that do not affect how the roof works.
The carrier pays for functional damage, and an inspection is how you find out whether you have it
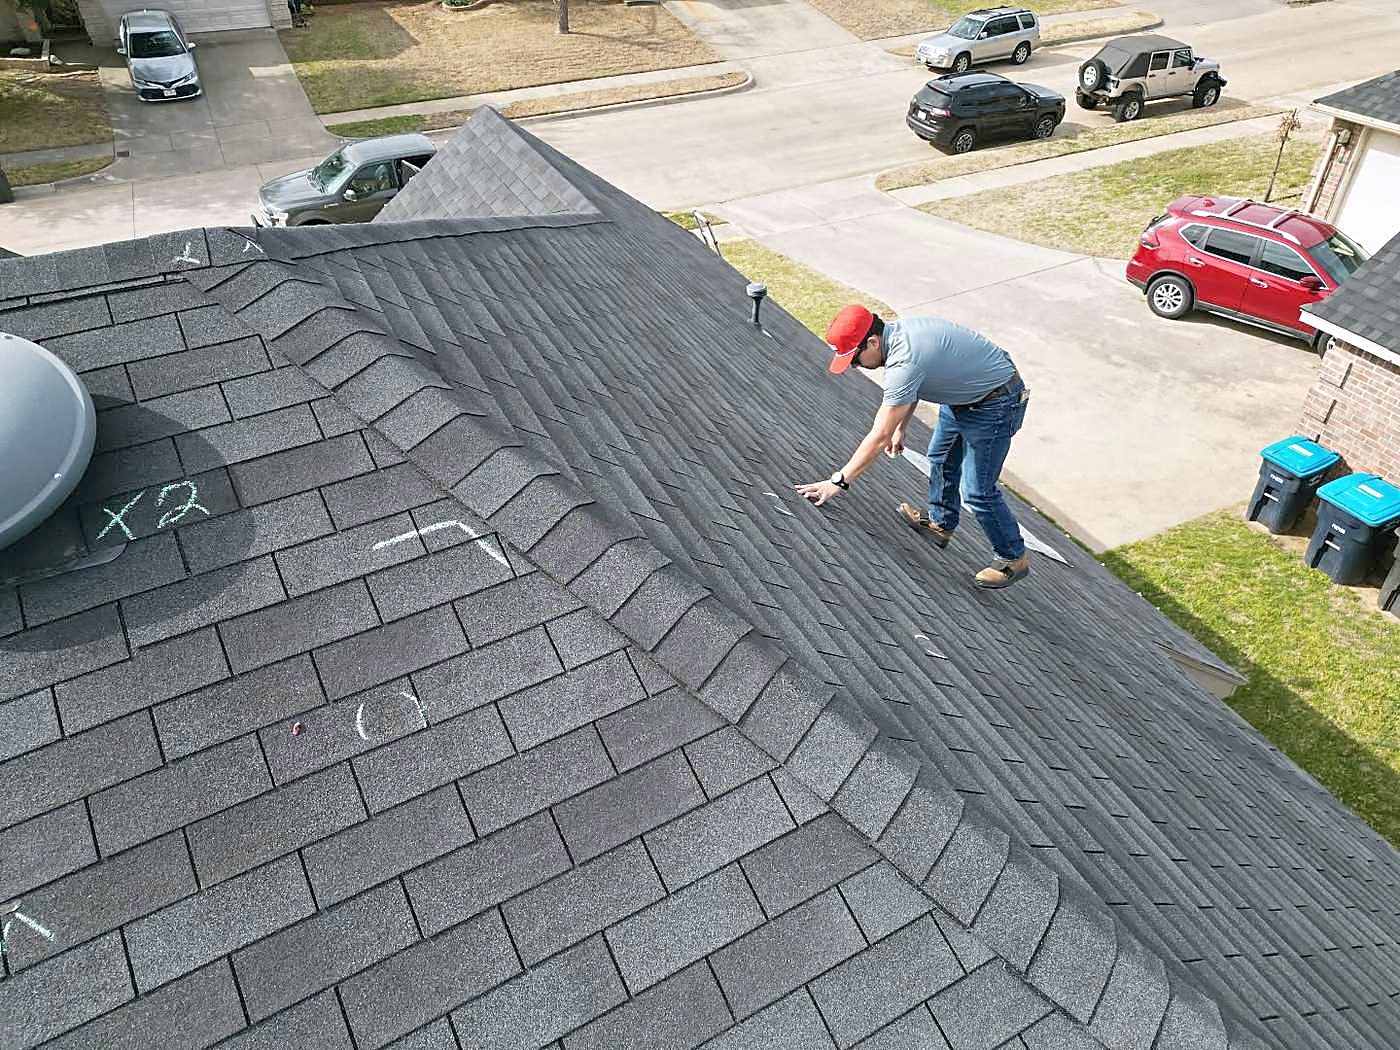
Hail that bruises a shingle, cracks it, or knocks enough granules loose to expose the asphalt has damaged the roof’s ability to shed water. That is what an adjuster is looking for. Dented gutters and vent caps help show hail size, but on their own they may not add up to a roof replacement.
A roofer’s inspection before you file tells you whether that damage is present. It also gives you dated photographs, which matter because most policies require damage to be reported within a set time after the storm, and because the adjuster will ask when it happened.
Texas law makes the deductible yours to pay
A contractor offering to waive, absorb or rebate your deductible is breaking Texas law, and the homeowner can be exposed as well. Be wary of anyone at the door after a storm offering a free roof.
If the out-of-pocket portion is a strain, ask about payment plans instead. Gregory Group Roofing offers them.
A denial is not always the last word
Claims are sometimes denied on the grounds that damage is old, is wear and tear, or was not caused by the storm. When the damage is documented properly, a carrier can be asked to re-inspect, and denials are sometimes reversed on that second visit. Your policy also describes an appraisal process for disputes over the amount of a loss.
Related questions
How long do I have to file a hail claim in Texas?
Policies set their own reporting deadlines, often one or two years from the date of the storm. Check your policy, and report sooner rather than later.
Will one hail claim raise my premium?
It can, depending on the carrier and your history. Ask your agent before you file.